


Kikoff - Build Credit Quickly
4.816.82K Reviews
App Specs
- Version
- 1.181.3223
- Updated On
- License
- Free
- Downloads
- 5,000,000+
- Developer
- Kikoff Inc.
- Categories
- Finance
- Platform
- Android, iOS
Screenshots
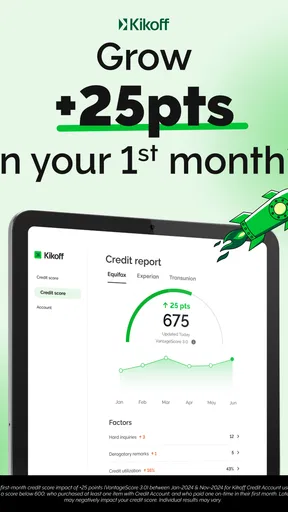
 Analysis by AppCompare
I’m cautious about any app that makes improving credit sound effortless, so I’d look at Kikoff less as a shortcut and more as a structured way to begin building a credit history. Its central idea is to give users a credit line for small purchases, creating a chance to demonstrate responsible credit use. That focus can be useful if you’re new to borrowing, but it also means the app works best when you understand what it can and cannot do: consistent use is not the same as an instant score boost.
What the credit-building approach means in practice
For someone with little credit history, the challenge is often a loop: lenders want to see responsible borrowing, while a new borrower may have few opportunities to demonstrate it. Kikoff’s approach is to make a modest credit activity part of the routine. I’d treat that activity as a training ground for habits—keeping track of what I use, following the terms, and avoiding the assumption that simply signing up guarantees a particular result.
That distinction matters because credit scores reflect broader information, and one app cannot make every part of a financial profile look stronger. Kikoff may be a starting point, not a replacement for paying other obligations on time or keeping an eye on existing balances. If I were trying it, I’d first decide what specific gap I’m addressing: no established history, a desire for a more deliberate routine, or simply a need to learn how credit works. That goal helps me judge whether the app is doing something useful for me.
The app is free to download, but I would still read the current terms for the credit-building service before committing to any plan or purchase. A free app does not automatically mean every service inside it is free, and financial products deserve a careful look at costs and conditions. I’d also avoid budgeting around a promised score change. A more realistic expectation is that responsible activity may support a longer-term effort, while the timing and outcome depend on a person’s overall credit picture.
A routine that is easier to manage than a new card
Compared with a traditional credit card, this route may feel more contained for a person who does not want a general-purpose card in their wallet. A card can be more flexible for everyday spending, but that flexibility can also make it easier to spend beyond a plan or carry a balance. A focused credit-building product may be simpler to keep separate, provided its purchase options and terms suit the user.
It is not automatically a better choice than a secured card or another credit-building service. Someone who needs a payment card for regular expenses, wants a broader range of purchases, or is comparing several ways to establish credit should weigh those options side by side. The useful question is not which method sounds easiest; it’s which one fits a person’s budget and is simplest to manage reliably month after month.
A practical tip I’d use is to set a recurring reminder for the date I need to review activity, rather than assuming the app will handle every decision for me. I’d check what I bought, confirm that the amount makes sense for my budget, and keep a note of any relevant payment or account dates. That small check-in can prevent a credit-building routine from becoming a forgotten subscription or a purchase I wouldn’t otherwise make.
Worth Reading Before You Choose

EA SPORTS FC Mobile 26 Is a Bigger Football Game, but It Takes Time

Flipboard Shows What News Apps Must Do Beyond the Feed

Switching to Android Auto Means Rethinking Your Driving Routine

Google Calendar Makes a Crowded Week Easier to Manage

Ludo King Makes the Most of the Minutes Between Plans

Baby Panda World Brings Quick Play to Modern Phones, but Its Game Library Feels Busy
Who is likely to get the most from it
Kikoff is most appealing to someone who wants a guided first step and is comfortable using a defined service rather than opening a standard credit card. It may also suit a person who likes keeping financial tasks on a phone and wants credit education alongside the activity. The developer is Kikoff Inc., and the app is listed in the finance category; its 4.8 average across around 122,000 ratings and more than five million installs suggest that many people have found it worth trying, though those figures cannot predict an individual outcome.
I’d be less likely to recommend it to someone who already has several credit accounts to manage, needs a broad spending tool, or is looking for immediate relief from debt. It is not a debt payoff plan, and starting a new credit activity does not resolve missed payments or high balances elsewhere. If the main issue is existing debt, a budget review or reputable nonprofit credit counseling may be a more relevant first move than opening another product.
For a realistic example, imagine a person who has just started working and has no established credit file. They could use a small, planned purchase as a monthly prompt to learn how credit activity fits into their finances, while continuing to pay rent, utilities, and other obligations on schedule. The key is not to buy something merely to generate activity. If the available items do not meet a real need, I’d rather skip a purchase than spend money for the sake of feeling productive.
Details I’d check before making it a habit
Before using any credit-building app, I’d look for clear explanations of the account terms, what is reported, what fees may apply, and what happens if I stop using the service. Those are the practical questions that determine whether a product fits, and they are more important than a smooth onboarding screen. I’d also make sure the app’s explanation matches my own records, especially if I already monitor credit through another service.
Credit information can take time to reflect changes, so I wouldn’t judge Kikoff by checking a score every day. If I used it, I’d review progress at sensible intervals and keep expectations modest. A score can move for reasons unrelated to one new account, and different services may show different versions of a score. For me, the more useful measure would be whether I’m sticking to a manageable routine and understanding my credit obligations better.
The app is free and carries an Everyone age rating. It was released on March 25, 2021, and version 1.170.2795 lists Android 7.0 as its minimum operating-system requirement. Those details help with basic compatibility, but they don’t answer the personal question of whether the service suits your finances. I’d check that my device can run it, then focus on the terms and the kind of credit activity I actually need.
If you're like me, always on the lookout for ways to boost your credit score without jumping through hoops, Kikoff might just be your new best friend. This nifty app, available for both Android and iOS, promises to help you build credit quickly and painlessly. Let me take you through my experience with it and see if it lives up to the hype.
Getting Started with Kikoff
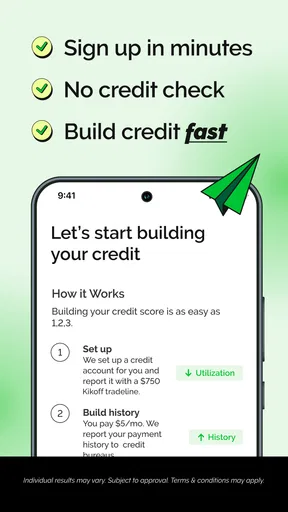
Diving into Kikoff was as easy as pie. The app’s interface is clean and user-friendly, which is a big plus if you’re not exactly tech-savvy. Signing up was a breeze; it took me less than five minutes. All you need is some basic info, and you're good to go. It's like setting up an online shopping account, just without the temptation to buy things you don't need!
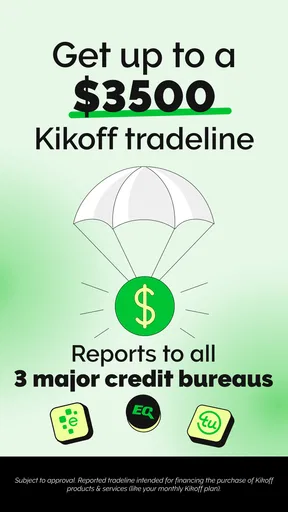
Once you're in, Kikoff offers a simple plan to help you start building your credit. It works by opening a line of credit for you, which you can use to make small purchases. The idea is to show that you can manage credit responsibly, which is key for boosting your credit score. And don't worry, they give you all the guidance you need to make sure you’re using this service effectively.
The Benefits of Using Kikoff
What I absolutely love about Kikoff is how affordable it is. Seriously, it costs less than a cup of coffee per month! This makes it accessible to just about anyone, which is fantastic if you're on a tight budget but still want to work on your credit.
Another cool feature is the educational content. Kikoff doesn’t just let you build credit; it also teaches you about it. The app provides insights and tips on credit management, which is super handy if you're new to the whole credit game. It's like having a mini financial advisor in your pocket!
Oh, and did I mention there are no hidden fees? Transparency is a huge deal for me, and it’s clear that Kikoff values that too. You know exactly what you're getting into, which is rare these days.
Using Kikoff Day-to-Day
Using Kikoff is surprisingly easy. Every month, you make a purchase from their online store, and that amount is what gets reported to the credit bureaus. The store has a range of digital products, and while you might not find everything you want, the selection is decent enough to make your monthly spend worthwhile.
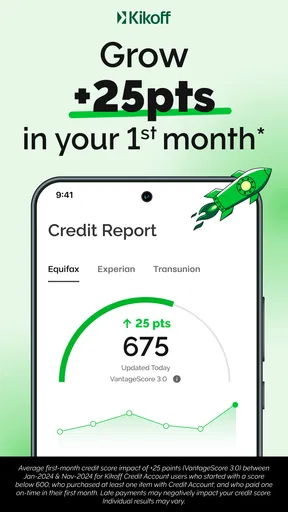
One thing to keep in mind is that patience is key. Building credit isn’t an overnight process, but with Kikoff, you’re on the right track. I started noticing improvements in my credit score within a few months. It’s a steady climb, not a sprint, but trust me, it’s so worth it.
Final Thoughts
If you're looking for an easy, low-cost way to start building your credit, Kikoff is definitely worth checking out. The app is straightforward, the costs are minimal, and the potential benefits are significant. Plus, you get to learn a thing or two about managing credit along the way.
While it might not be for everyone—especially if you’re looking for something that provides instant results—Kikoff offers a solid foundation for anyone just starting their credit-building journey. It's like planting a tree; it takes time to grow, but eventually, you'll have something strong and enduring. So, why not give it a try? Your future self will thank you!
Pros
- Simple
- user-friendly interface.
- Low monthly fee for services.
- No hard credit check required.
- Accessible to those with limited credit history.
- Offers personalized credit tips.
Cons
- Limited to U.S. residents only.
- No direct access to credit cards.
- May take time to see significant changes.
- Customer support can be slow.
- Limited features compared to competitors.
FAQs for Kikoff - Build Credit Quickly
What is Kikoff, and how does it help build credit?
Kikoff is a financial app designed to help users build and improve their credit scores quickly and efficiently. By offering a revolving line of credit, Kikoff enables users to make small purchases that are reported to major credit bureaus, thereby helping to establish a positive credit history. It’s an ideal solution for those new to credit building or looking to repair their credit scores.
Is Kikoff safe to use, and how does it protect my personal information?
Kikoff prioritizes user security by employing industry-standard encryption and security measures to protect personal and financial information. The app is designed with privacy in mind, ensuring that user data is never shared with third parties without consent. Additionally, Kikoff is compliant with all relevant regulations, providing peace of mind for users concerned about data protection.
How much does it cost to use Kikoff, and are there any hidden fees?
Kikoff offers a straightforward pricing model with no hidden fees, making it accessible for users seeking to build credit. There are no annual fees, interest charges, or late fees associated with the service. Users pay a minimal monthly fee, which provides access to the credit line and other features designed to improve credit health.
Can Kikoff affect my credit score negatively?
Using Kikoff responsibly can positively impact your credit score. However, as with any credit product, failing to make timely payments or mismanaging your credit utilization can lead to negative effects. Kikoff provides tools and reminders to help users maintain good credit habits, ensuring that the app serves as a beneficial tool for credit improvement.
What are the requirements to sign up for Kikoff, and how do I get started?
To sign up for Kikoff, users must be at least 18 years old, have a valid Social Security number, and reside in the United States. The sign-up process is straightforward and can be completed through the app or website. Once registered, users can immediately begin utilizing the credit line to make purchases and start building their credit profile.


